
Do you need to prove negligence?
No
strict liability applies
Who is liable?
Manufacturer
or importer / retailer
Time limit
3 years
10-year longstop
Upfront cost
£0
No Win No Fee basis
Written by

Azhar Ali
Personal Injury Solicitor at Claim Time Solicitors, Birmingham. Handling personal injury and child injury claims across England and Wales on a No Win No Fee basis.
This guide is reviewed against current UK statute including the Occupiers’ Liability Acts 1957 and 1984, Judicial College Guidelines (18th edition, April 2026), and SRA standards. It is for general information only and does not constitute legal advice.
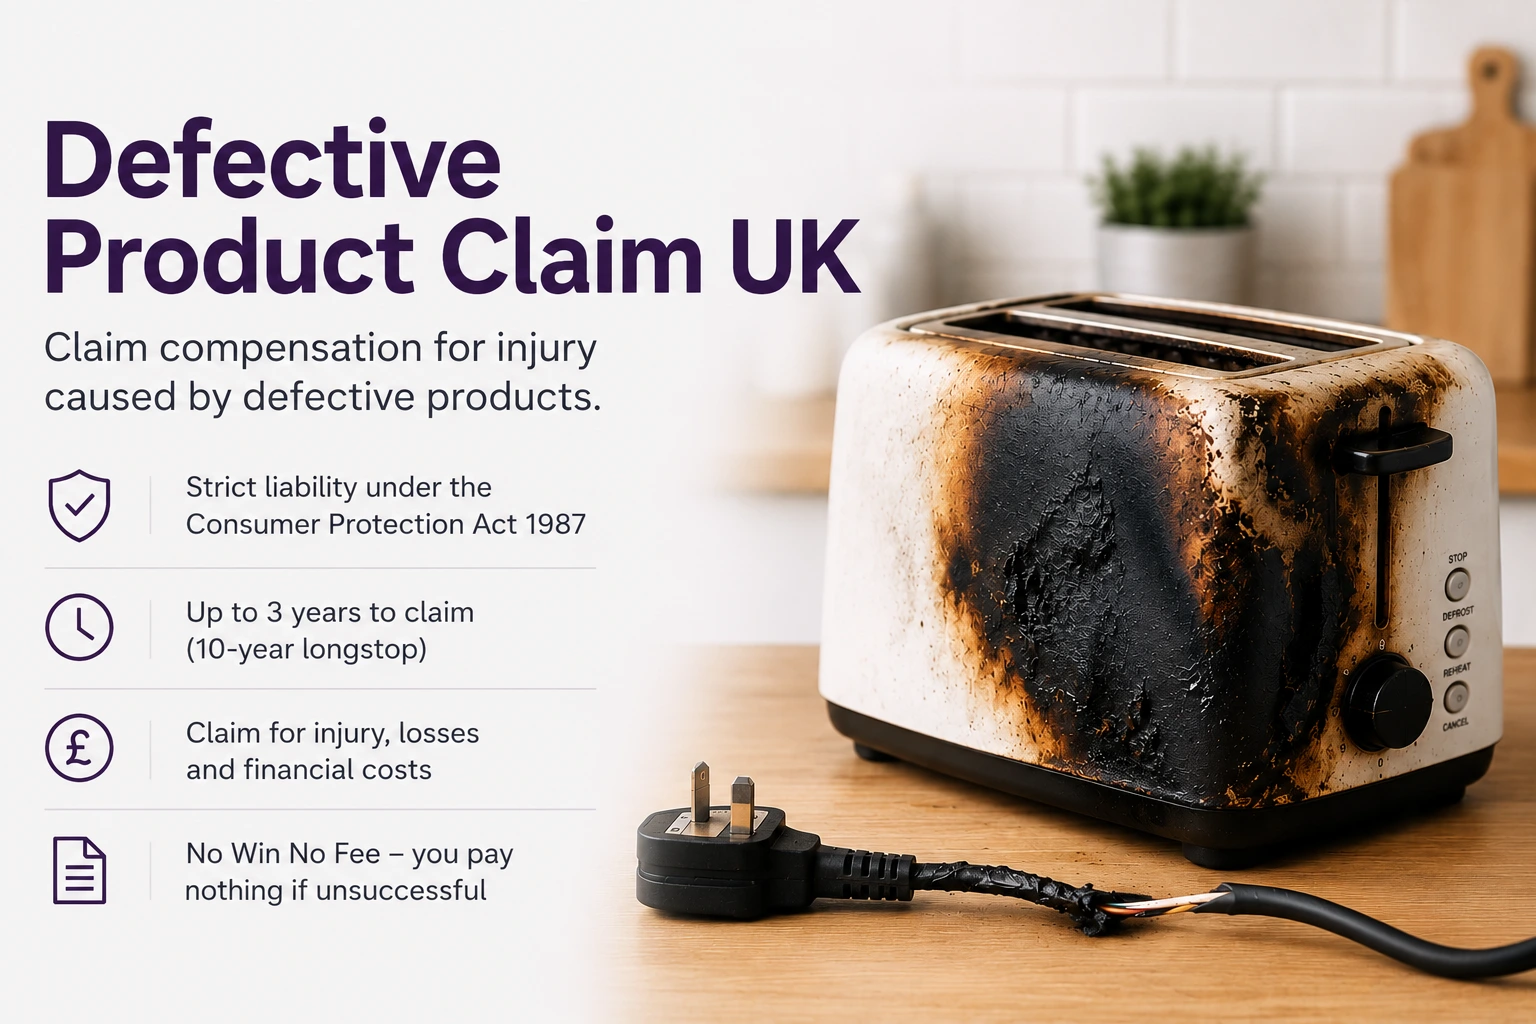
If a product you bought or used was defective and that defect caused you injury, you can make a defective product claim in the UK under the Consumer Protection Act 1987. You do not need to prove the manufacturer was negligent, only that the product was defective and the defect caused your injury. This is called strict liability. The claim goes against the producer, an own-brander or the importer, and against the retailer only where they cannot identify any of those when asked. Most defective product claims are handled on a No Win No Fee basis.
A product you trusted caused you harm. Whether it was a faulty electrical appliance, a contaminated food product, a children’s toy that broke in a dangerous way, or a cosmetic that caused a chemical burn, the law gives you the right to claim compensation when a defective product causes injury. The Consumer Protection Act 1987 places the responsibility on the producer, not on you and you do not need to prove they were careless. You only need to prove the product was defective and the defect caused your injury.
This guide explains how a defective product claim works in the UK, who is liable, what the law actually says, what compensation covers, and what to do if you have been injured by a product that was not safe.
Can I claim for a defective product?
To make a defective product claim in the UK, you need to establish three things: the product was defective, you suffered injury or damage, and the defect caused the injury. You do not need to prove how the defect happened or that the manufacturer was careless.
The Consumer Protection Act 1987 (CPA 1987) created a strict liability regime for defective product claims in the UK. This means the question is not whether the manufacturer took reasonable care it is whether the product was defective. If it was, and that defect caused your injury, the manufacturer is liable regardless of how or why the defect occurred.
This is a significant legal advantage for anyone making a defective product claim. In most personal injury claims, you must prove the other party was negligent that they failed to take reasonable care. Under the CPA 1987, that burden does not apply. The focus is on the product itself, not on the manufacturer’s behaviour.
What counts as a defective product in UK law?
A product is defective under the CPA 1987 if its safety is not what a person is generally entitled to expect. This is an objective test — it looks at what a reasonable consumer would expect, not what the manufacturer intended.
The courts consider several factors when assessing whether a product meets the safety standard consumers are entitled to expect: how the product was marketed and presented, what instructions and warnings were provided, what a reasonable consumer would do with the product, the price point and any implied quality expectations, and the state of scientific and technical knowledge when the product was supplied.
A product does not need to be recalled to be legally defective. A product recall is a decision by the manufacturer or a regulatory body it is not the same as a legal finding of defect. Many defective product claims succeed against products that were never recalled. Equally, a product being recalled does not automatically mean a claim will succeed — the claimant must still show the defect caused their specific injury.
Key concept
Three types of product defect
Manufacturing defect: the product departed from its intended design during production. One unit is faulty while others are fine.
Design defect: the product was manufactured exactly as designed, but the design itself is unsafe. Every unit carries the same risk.
Warning/instruction defect: the product lacks adequate warnings, safety instructions, or information about risks that a consumer needs to use it safely.
Who is liable for a defective product in the UK?
| Party | When they are liable | Example |
|---|---|---|
| Producer (manufacturer) | Primary liability, if the product is defective | A UK manufacturer whose kitchen appliance causes a fire |
| Importer into the UK | Liable when they brought the product into the UK from outside | A UK distributor who imports electronics from China |
| Own-brander | Liable when they put their name or brand on the product | A supermarket own-brand product manufactured by a third party |
| Retailer / supplier | Liable only if they cannot identify the manufacturer or importer when asked | A retailer who sells unbranded goods and cannot trace the source |
This chain of liability is designed to help identify a responsible party in a defective product claim. Even if the manufacturer is based overseas and difficult to reach, the UK importer who brought the product into the country is liable in their place. If neither can be identified, the retailer who sold you the product may be held responsible — unless they can identify the producer or importer within a reasonable time of being asked.
Strict liability: why you do not need to prove negligence
Strict liability under the CPA 1987 is the single most important concept in any defective product claim in the UK. It means the manufacturer is liable for damage caused by a defective product regardless of whether they were negligent, regardless of whether they took reasonable care, and regardless of whether the defect was foreseeable.
The manufacturer has one principal defence: the development risks defence (also known as the state of the art defence). This applies only if the manufacturer can show that the state of scientific and technical knowledge at the time the product was supplied was such that a producer of products of the same description could not have been expected to discover the defect. This is a narrow defence and rarely succeeds in practice for consumer products
Claiming against the shop or the manufacturer: which law applies?
There are two separate routes and they point at two different people. Most readers need both, and being sent from one to the other is the most common thing that goes wrong.
Against the retailer, under the Consumer Rights Act 2015. Section 9 treats every contract to supply goods as including a term that the quality of the goods is satisfactory, and s.9(3) spells out what quality includes, with safety and durability both on the list. Section 3(1) is what makes that bite on the shop: the Chapter applies to a contract for a trader to supply goods to a consumer, so the term sits in your contract with whoever sold you the goods rather than with whoever made them. This is the route for the product itself: repair, replacement, or rejection and a refund.
So when a retailer tells you that because the item is a medical device, or an appliance, or came from a particular brand, you must take it up with the manufacturer, that is not the legal position. The retailer may well arrange for the manufacturer to carry out a repair as its agent, and there is nothing wrong with accepting that as the quickest route, but the responsibility under the contract stays with the retailer.
Against the producer, under the Consumer Protection Act 1987. Section 2(2) makes the producer liable, and with them anyone who put their own name or trade mark on the product and anyone who imported it into the UK in the course of business. Where more than one of them is liable for the same damage, section 2(5) makes that liability joint and several, so you do not have to work out which of them was at fault.
If you cannot identify any of them, section 2(3) gives you a route through the supplier. Ask the shop in writing to identify the producer, own-brander or importer. If it fails to do so within a reasonable period, the shop itself becomes liable. That provision exists precisely for the situation where a product arrived with no traceable maker, and it is worth using rather than giving up.
This is the route for the injury and for damage to your other property, and it does not require you to prove anyone was careless.
Which one you need. If the product broke and you want your money back, the Consumer Rights Act and the retailer. If the product injured you or wrecked something else you own, the Consumer Protection Act and the producer. If both happened, both routes run at once, against different parties, and they do not conflict.
Common types of defective product claims in the UK
- Electrical appliances, overheating, electrical shock, fire caused by faulty wiring, battery failure. Includes kitchen appliances, chargers, heaters, and personal care devices.
- Children’s toys and products, small parts that detach and pose choking hazards, toxic materials, sharp edges, collapsible structures. Subject to additional safety regulations under the Toys (Safety) Regulations 2011.
- Food and drink, contamination (foreign objects, bacteria, allergens not declared on labelling). Covers packaged food, restaurant meals, and takeaway items.
- Cosmetics and personal care products, chemical burns, allergic reactions, skin damage from undeclared ingredients or unsafe formulations.
- Vehicles and vehicle components, brake failure, airbag defects, seatbelt failure, tyre blowouts, steering column faults. Can overlap with road traffic accident claims.
- Medical devices, implant failure, prosthetic defects, faulty monitoring equipment. Subject to additional regulation under the Medical Devices Regulations 2002, amended from June 2025 to add post-market surveillance requirements.
- Furniture and household items, collapse, structural failure, fire risk from non-compliant materials. Includes mattresses, chairs, shelving, and garden furniture.
- Pharmaceutical products, undisclosed side effects, contamination, incorrect dosage information. Pharmaceutical defective product claims are complex and often involve group litigation.
This covers contamination, foreign objects, undeclared allergens and incorrect labelling. A food product that makes you ill is a defective product in the same way a faulty appliance is, and the same strict liability applies: you do not have to show the producer was careless, only that the product was not as safe as people generally are entitled to expect.
Electrical products and appliances
These are the claims where the damage to your other property is often worth more than the injury, and where section 5(2) of the Consumer Protection Act 1987 decides what you can recover. The Act covers the fire damage to your home and its contents, provided the property damage exceeds £275, but it does not cover the appliance that caused the fire. For the appliance itself you are looking at the retailer under the Consumer Rights Act 2015.
Preserve the product if you can do so safely, even burnt out, and keep the packaging, the charger and the receipt. In electrical cases the cause is normally established by an engineer examining the item, and a claim becomes far harder once it has gone to the tip.
Food and drink
This covers contamination, foreign objects, undeclared allergens and incorrect labelling. A food product that makes you ill is a defective product in the same way a faulty appliance is, and the same strict liability applies. You do not have to show the producer was careless, only that the product was not as safe as people generally are entitled to expect.
Food is the category where a recall is most often the first you hear of a problem. If you were ill before a recall was announced, the recall does not create your claim, but it is useful evidence that the defect existed.
Garden and outdoor equipment
Lawnmowers, strimmers, hedge trimmers, pressure washers and powered tools. The defects that recur are guarding that fails or was never adequate, blades that detach, and switches that do not cut power when released.
Where the tool was supplied for use at work, there is often a claim against the employer as well as against the producer, and the two are not alternatives. An employer has duties over the equipment it provides that are separate from the producer’s strict liability for a defect, and a claim can run against both.
Lithium-ion batteries, e-bikes and e-scooters
Battery fires are now a regulatory priority. The London Fire Brigade attended 206 e-bike and e-scooter fires in London during 2025, which it describes as a record, up from 78 in 2021. Two people died, taking London’s total to five since 2023. Nationally, the Office for Product Safety and Standards was notified of 267 such fires during 2025, 86 of which happened while the product was on charge. Of the 217 involving e-bikes, 82 were bikes converted with an aftermarket kit. Reporting to OPSS by fire services is voluntary, so the actual numbers may be higher, and OPSS cautions against reading year-on-year trends into its figures.
The practical difficulty is identifying who to claim against. If a battery, charger or conversion kit caused the fire, the claim runs against whoever produced or imported the component that failed, which is frequently not the brand on the bike. Section 2(3) of the Consumer Protection Act 1987 gives you a route through the seller, who becomes liable itself if it cannot name the producer or importer when asked in writing.
Household goods and furniture
Collapsing furniture, glass that shatters, cots and highchairs, and products that fail in ordinary use. The test is the same across every category above. Not whether the product was perfect, but whether its safety was what people generally are entitled to expect, judged against how it was marketed, what warnings and instructions it carried, and what might reasonably be expected to be done with it.
What to do after a product injures you
- Get medical attention — see a GP or attend A&E the same day. Ask the doctor to record the product as the cause of injury in your medical notes. The medical record is the primary evidence in any defective product claim.
- Preserve the product — do not throw away, repair, or return the product. Keep it exactly as it was when the injury occurred. Store it safely. The product itself is evidence of the defect.
- Photograph everything — the product, any visible defect, the packaging, batch numbers, serial numbers, and your injuries. Photograph before any cleanup or repair.
- Keep the receipt and packaging — proof of purchase, packaging, instruction manuals, and warranty documents all help identify the manufacturer and establish when the product was supplied.
- Report the product — report to the retailer in writing. You can also report to Trading Standards or the Office for Product Safety and Standards (OPSS). A formal report creates an official record.
- Do not contact the manufacturer’s legal team directly — they may ask you to return the product or sign a release. Speak to a solicitor before engaging with the manufacturer.
- Contact a solicitor — a solicitor experienced in defective product claims can advise on preserving evidence, identifying the liable party, and starting the claim process.
Manufacturers and retailers sometimes ask you to return the defective product for investigation or replacement. Do not do this without legal advice. Once the product is back in the manufacturer’s possession, you lose control of the primary evidence in your defective product claim. A solicitor can arrange independent examination of the product while keeping it in safe custody.
Do you have a valid defective product claim?
Answer four quick questions to receive clear guidance based on your circumstances.
How much compensation for a defective product claim UK?
Compensation covers general damages for the injury itself (assessed under the JCG 18th edition, April 2026) plus special damages for all financial losses caused by the defective product. Property damage claims under the CPA 1987 have a £275 minimum threshold.
| Injury type | Indicative range |
|---|---|
| Minor burns — full recovery | £2,430 to £8,290 |
| Serious burns — scarring, permanent | £32,450 to £97,730 |
| Minor soft tissue — full recovery | £800 to £4,270 |
| Eye injury — minor, full recovery | £4,270 to £9,760 |
| Eye injury — total loss of one eye | £61,690 to £72,430 |
| Food poisoning — serious, lasting effects | £4,270 to £10,730 |
| Moderate psychiatric — PTSD | £6,470 to £22,510 |
All figures are indicative from the Judicial College Guidelines (JCG), 18th edition (April 2026). Every defective product claim is assessed individually. Special damages are calculated separately and added where appropriate.
Compensation has two halves, and on a serious product injury the second half is usually the larger one.
General damages pay for the injury itself, the pain and the loss of amenity. They are assessed against the Judicial College Guidelines, now in their 18th edition, published on 9 April 2026, which raised the brackets by around 8.26 per cent to reflect inflation to August 2025.
That date matters when you are comparing figures. The previous edition came out in March 2024 and was set against inflation only to August 2023. So a compensation figure published before April 2026 is working from a two-and-a-half-year-old inflation measure, and understates the current bracket by roughly a twelfth.
Special damages pay for what the product actually cost you, and they are calculated from evidence rather than from a bracket. On a product injury these are often unusual, and they are the ones most frequently missed: the cost of replacing other property the product destroyed, temporary accommodation if a fire made your home uninhabitable, private treatment, travel to appointments, lost earnings, and the value of care given to you unpaid by family.
There is one threshold specific to product claims and it catches people out. Section 5(4) of the Consumer Protection Act 1987 means no damages are awarded for loss of or damage to property where the amount would not exceed £275. That threshold applies to property damage only. It does not apply to death or personal injury, so a modest injury claim is not shut out by it.
Section 5(2) sets a second limit that surprises people more. The Act does not compensate you for the defective product itself. If a kettle fails and scalds you, the Act covers the burn and the kitchen it damaged, not the kettle. For the kettle you have a separate claim against the retailer, which is the section above.
Time limits: the 3-year deadline and the 10-year longstop
You have three years from the date of injury or from the date you became aware the injury was caused by the defective product (the date of knowledge). But there is also a 10-year longstop from the date the product was first supplied after which the right to claim under the CPA 1987 expires completely.
The three-year limitation works the same way as other personal injury claims — it runs from the date of the accident or from when you first knew (or should reasonably have known) that the injury was caused by the product. The 10-year longstop is unique to defective product claims under the CPA 1987. It creates an absolute cut-off regardless of when the injury occurred or when the claimant became aware of it.
For children, the three-year clock does not start until their 18th birthday, but the 10-year longstop still applies from the date the product was supplied. This means a child injured by a product supplied more than 10 years ago may have no claim under the CPA 1987, even if the three-year limitation has not yet expired. A solicitor can advise on alternative routes, including common law negligence claims, where the longstop does not apply.
Product liability law is being rewritten: what the Law Commission is proposing
The law this page describes is under formal review, and the proposals would change it substantially.
On 8 October 2026 the Law Commission published proposals for a major overhaul of product liability law and opened a consultation that runs until 14 January 2027. Final recommendations are expected in late 2027. The review focuses on Part 1 of the Consumer Protection Act 1987, which is the strict liability regime set out above. The project is sponsored by the Department for Business, Innovation, Science and Trade. The Commission’s view is that the Act was built for a world of physical goods and has not kept pace with products that are digital, connected and complex.
The proposals that matter most to someone injured by a product are these.
Online marketplaces would become liable. At present a consumer who buys from a marketplace listing often cannot identify a producer or a UK importer at all, which is the single biggest practical obstacle to a claim. The proposals would extend liability to online marketplaces.
Software and AI systems would be products in their own right, whether supplied on or embedded in a device, downloaded, or accessed remotely. The design components and features of social media platforms would also fall within scope, including recommendation systems such as algorithms.
The ten-year longstop would reset after a substantial modification. The proposals include clarification of liability where a product has been substantially modified after supply, and a reset of the longstop period where the producer makes that modification. The definition of supply would also be expanded to cover delivery by download.
Psychiatric harm would be clearer. The proposals include clearer rules on when compensation is available for psychiatric illness, both for people directly harmed by a defective product and for people who develop it after witnessing harm to, or the death of, a loved one. In fire and burn cases that is a real and currently difficult question.
Proving a defect would get easier in some cases. Where claimants face exceptional difficulty obtaining evidence, a presumption of defectiveness would apply in limited circumstances. A defendant could rebut it, or accept it and pay partial compensation under a new risk-sharing mechanism.
The existing defences would be kept. The Commission proposes retaining them subject to updates so that they continue to work effectively. It has not yet published what those updates would be. Under the development risks defence as it stands, a producer is not liable for a defect that could not have been discovered when the product was supplied.
What this means for a claim you are bringing now
None of this is law yet, and none of it changes a claim you are bringing today. It matters for two reasons. If you are deciding whether to act now, the current three-year limit and the ten-year longstop still apply, and waiting for reform is not a strategy. And if you were injured by something bought through a marketplace and could not identify a producer, that obstacle is one the Commission has specifically identified.
Product safety regulation is moving separately, and faster
The Product Regulation and Metrology Act 2025 received Royal Assent on 21 July 2025. Most of it took effect that day, but section 11(1) and (3), which amend the Consumer Protection Act 1987 and the Weights and Measures Act 1985, come into force only on a day the Secretary of State appoints by regulations, and that day has not yet been appointed.
The Act does not change product liability itself. It gives government the power to make product safety regulations, and those powers are already being used. On 13 April 2026 the Department for Business and Trade launched three consultations under them: two on reform of the product safety framework, including consolidating market surveillance and enforcement powers, and one on furniture fire safety. All three closed on 23 June 2026. The proposals include new requirements for online marketplaces, which the department says have made third-party sales of dangerous products too easy, and the statement announcing them cites fatal house fires caused by unsafe e-bike batteries.
Food, plants, medicines, medical devices and aircraft components are outside the Act’s scope and remain under existing rules. The General Product Safety Regulations 2005 continue to apply.
Summary
A defective product claim in the UK is brought under the Consumer Protection Act 1987, which imposes strict liability on manufacturers. You do not need to prove the manufacturer was negligent — only that the product was defective and the defect caused your injury. The liable party is the producer, or if the product was imported, the importer. If neither can be identified, the retailer may be held responsible.
Compensation covers general damages for the injury under the JCG 18th edition plus special damages for all financial losses. The time limit is three years from injury or date of knowledge, with a 10-year longstop from when the product was first supplied. The most important step after a product injury is preserving the product itself — it is the primary evidence of the defect.
Key takeaways
- Strict liability applies — you do not need to prove the manufacturer was negligent. Prove the product was defective and the defect caused your injury.
- The manufacturer is primarily liable — or the importer, own-brander, or retailer if the manufacturer cannot be identified.
- Do not throw away or return the product — it is the primary evidence of the defect. Store it safely and do not repair or modify it.
- See a doctor the same day — the medical record linking your injury to the product is the most important clinical evidence.
- Report the product to the retailer in writing and to Trading Standards or OPSS.
- The time limit is three years from injury or date of knowledge — but a 10-year longstop applies from when the product was first supplied.
- A product does not need to be recalled to be legally defective — many successful defective product claims involve products that were never recalled.
- Property damage has a £275 minimum threshold under the CPA 1987 personal injury claims have no minimum.
Sources & References
- Consumer Protection Act 1987 — Part I — Introduces strict liability for damage caused by defective products, including the definition of a defect (section 3), liable persons (section 2), and the development risks defence (section 4).
- Limitation Act 1980, Section 11A — Sets the three-year limitation period for defective product claims together with the 10-year longstop period.
- Judicial College Guidelines for the Assessment of General Damages in Personal Injury Cases (18th Edition) — The guideline used by courts and practitioners when valuing general damages for personal injury claims.
- General Product Safety Regulations 2005 — Establishes the general safety requirement for consumer products placed on the UK market.
- Office for Product Safety and Standards (OPSS) — The UK’s product safety regulator responsible for market surveillance, recalls and reporting unsafe consumer products.
Frequently Asked Questions
Can I claim for a defective product in the UK?
Who is liable for a defective product?
What counts as a defective product?
How long do I have to make a defective product claim?
Three years from injury or date of knowledge. There is also a 10-year longstop from when the product was first supplied — after which the CPA 1987 right expires completely. For children, the three-year clock starts at 18, but the 10-year longstop still applies.
Do I need to prove the manufacturer was negligent?
No. The CPA 1987 operates on strict liability. You prove the product was defective, you suffered injury, and the defect caused it. You do not need to prove how the defect occurred or that the manufacturer failed to take reasonable care.
Should I return the product to the manufacturer?
Not without legal advice. The product is the primary evidence of the defect. Once it is back with the manufacturer, you lose control. A solicitor can arrange independent examination while keeping the product in safe custody.
Glossary of Key Terms
Disclaimer: The information on this page is for general guidance only and does not constitute legal advice. Compensation outcomes vary by individual case and depend on the specific facts and evidence. Claim Time Solicitors is authorised and regulated by the Solicitors Regulation Authority (ID No. 444171) and accredited by The Law Society . No Win No Fee refers to a Conditional Fee Agreement; the solicitor’s success fee is capped at 25% of compensation recovered. Terms apply.


